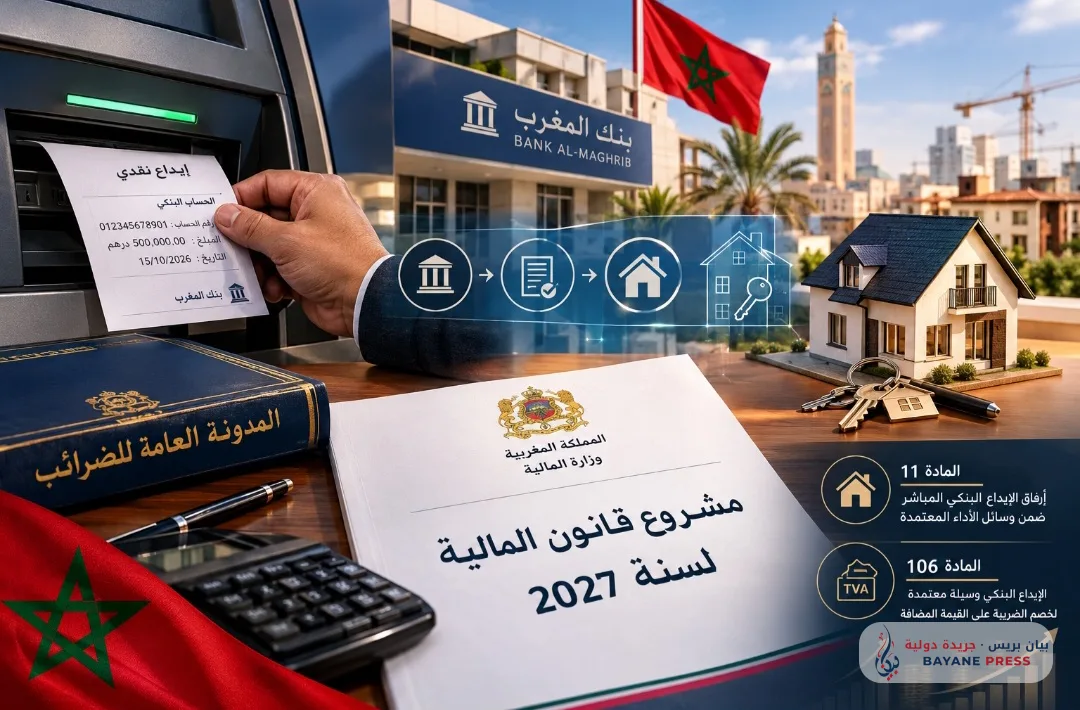
As part of the amendments to the 2027 Finance Bill, Morocco is moving towards expanding the list of tax-approved payment methods by explicitly recognizing direct bank deposits as mechanisms for settling financial transactions.
This initiative—representing an amendment to the second paragraph of Article 11 of the General Tax Code, scheduled to take effect in early January 2027—aims to resolve practical issues related to proving the payment of real estate prices. This is particularly relevant for transactions carried out via direct cash deposits into the bank accounts of sellers or real estate developers, rather than through inter-account bank transfers.
Previously, this method raised questions and inquiries among notarians, traditional legal professionals (adouls), and practitioners regarding whether direct deposit receipts were sufficient to avoid the imposition of supplementary registration duties at a rate of 2 percent on transactions exceeding 300 thousand dirhams.
This legislative recognition is expected to help clarify the conditions for proving payment and enhance reliance on documents issued by banking institutions that include account details, the amount, and the date of the transaction, while constantly ensuring that the actual payment is linked to the declared transaction and the identity of the parties involved.
Nevertheless, the direct impact of this new development on supplementary real estate registration fees remains tied to their specific provisions, as the acceptance of deposits for expense deductions does not necessarily mean total exemption from all fees in every real estate transaction.
These amendments are not limited to Article 11 alone; they also extend to Article 106 concerning Value Added Tax (VAT) deductions. Bank deposits have thus become an approved method enabling companies to settle invoices, purchases, and expenses of suppliers and service providers without facing deduction refusals, provided that legal and accounting conditions are met.
This new measure is expected to reduce tax risks during tax audits and alleviate administrative burdens on taxpayers. However, clarifying the scope of application and its direct relationship with real estate registration fees remains essential to unify interpretations, ensure legal certainty, and accurately distinguish between direct cash deposits and pure inter-account bank transfers.
Comments (0)
No comments yet. Be the first to react!