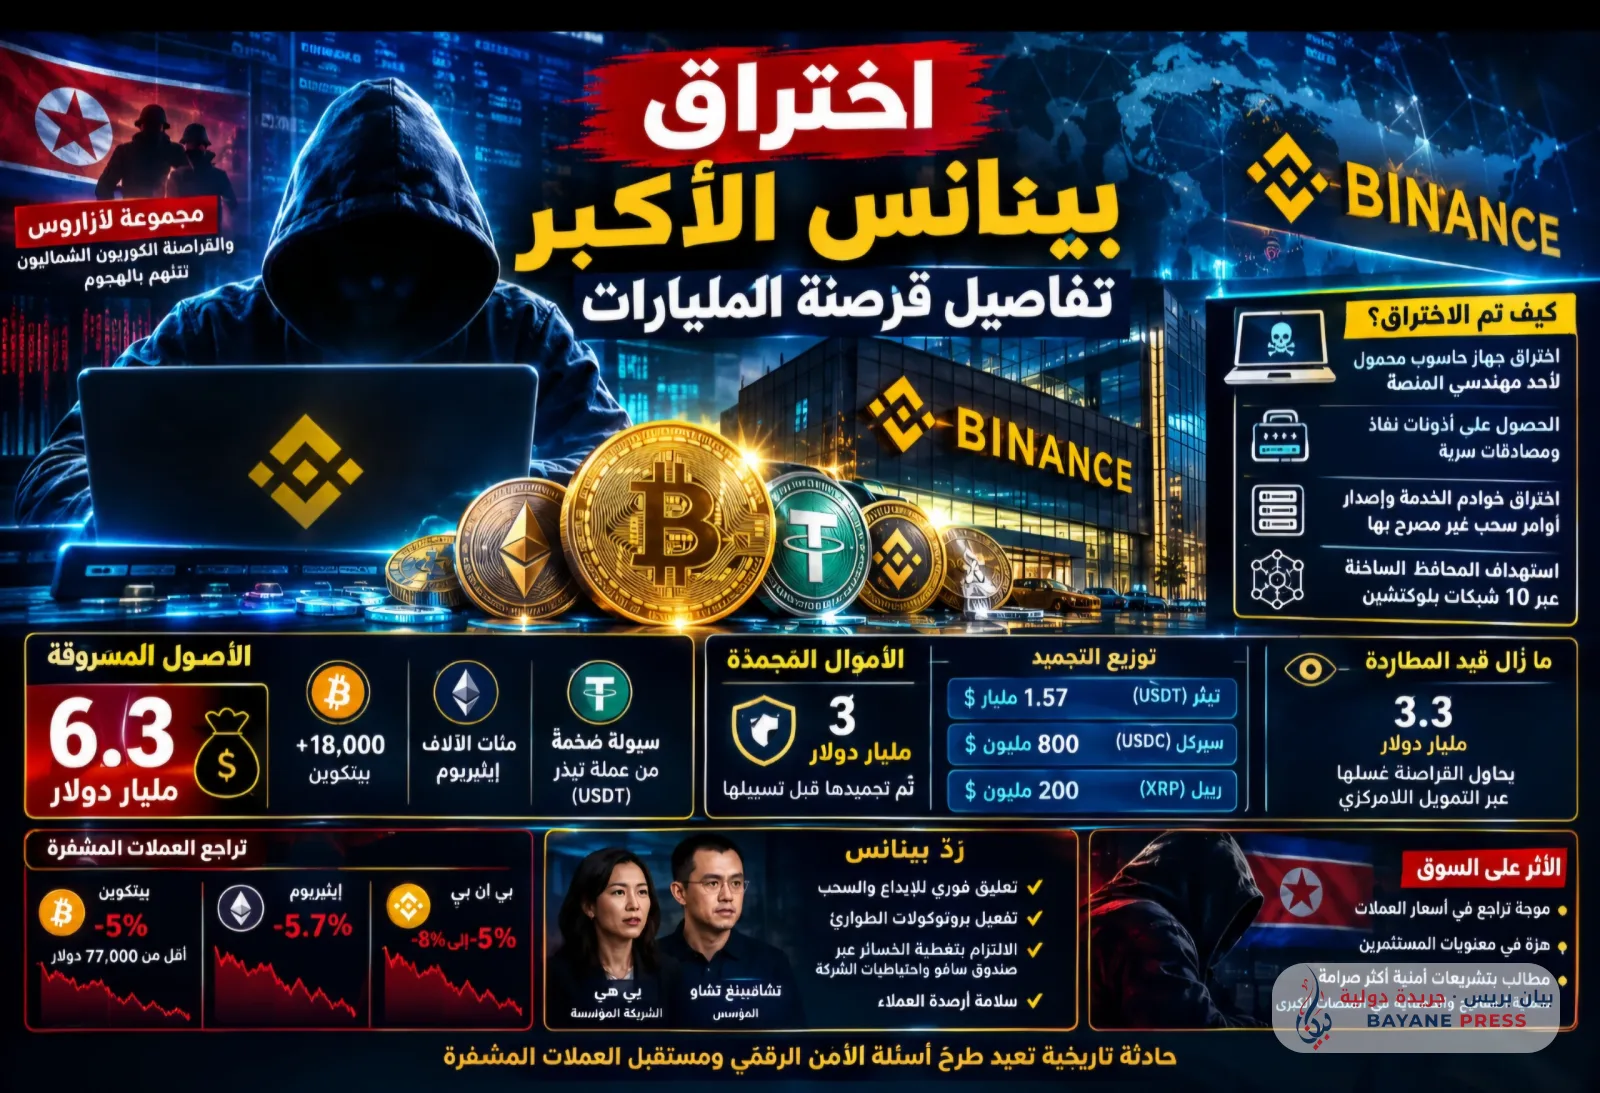
Financial and technological markets opened the most dangerous chapter in the history of cryptocurrencies as details emerged of the lightning-fast operation targeting Binance's infrastructure, resulting in the theft of digital assets estimated at approximately $6.3 billion in what has been described as the largest and most complex heist since the inception of blockchain technology. The breach did not stem from a software flaw in smart contract protocols, but rather began with a high-precision cyber breach of a laptop belonging to one of the platform's operations and infrastructure engineers, granting the hackers access permissions and secret authentications that allowed them to compromise service servers and issue unauthorized withdrawal orders targeting hot digital wallets simultaneously across 10 different blockchain networks in record time.
The stolen assets included a wide range of liquid cryptocurrencies, led by more than 18,000 Bitcoin units, hundreds of thousands of Ethereum coins, alongside massive liquidity in stablecoins, spearheaded by Tether. Major digital forensics analytics firms, including TRM Labs, Blockaid, and Chainalysis, concurred that the notorious North Korean hacking group Lazarus and TraderTraitor teams were behind the attack, based on technical fingerprints and complex transaction distribution methods designed to obscure tracking paths.
Facing the crisis, platform management activated maximum emergency protocols by immediately and comprehensively suspending deposit and withdrawal operations to isolate affected systems and secure databases. Concurrently, Binance led a swift defensive alliance with major trading platforms and stablecoin issuers to intercept the movement of funds, resulting in the freezing of about $3 billion before they could be liquidated. Tether led the charge by blocking over $1.57 billion, while Circle froze nearly $800 million in USDC, Ripple network suspended about $200 million, and security authorities and forensic tracking experts continue to pursue roughly $3.3 billion remaining, which the hackers are attempting to launder and dismantle via decentralized finance protocols to evade centralized freezing decisions.
Meanwhile, the platform's executive leadership, spearheaded by co-founder Yi He and founder Changpeng Zhao, moved to reassure users with a categorical confirmation that customer balances are safe and were not directly affected, announcing Binance's commitment to cover all self-unrecovered losses by activating the Secure Asset Fund for Users (SAFU) reserves and company funds to avert any liquidity or solvency crisis. However, the sheer magnitude of the incident dealt a violent blow to investor sentiment, as the cryptocurrency market witnessed an immediate slump where the price of Bitcoin dropped by about 5% to trade below the $77,000 level, Ethereum declined by nearly 5.7%, and the platform's native token BNB incurred direct losses ranging between 5% and 8%, renewing international regulatory demands to impose stricter security standards on key management and protection across major digital asset platforms.
Comments (0)
No comments yet. Be the first to react!